August – How long can the party last
Despite all odds, August came out to be a strong month, though marked by stark contrasts between sectors. Leading the pack was energy (+7.2%), pushed up by the Middle East conflict with seemingly no end in sight. Following closely was the return to favor of technology (+6.2%). At the bottom of the pack were utilities (-4.8%) and industrials (-2.6%). Robust second quarter corporate earnings are to be thanked for the good performance. There are, however, two sides to the coin. With high energy prices comes higher inflation, leading to central banks having a more hawkish stance. Down the road, higher interest rates are typically perceived as bad news for equities, even more so for growth stocks. To exacerbate the interest rate problem, long term rates (10+ years) are rising to levels not seen in a long time, but more on that in the chart of the month section.
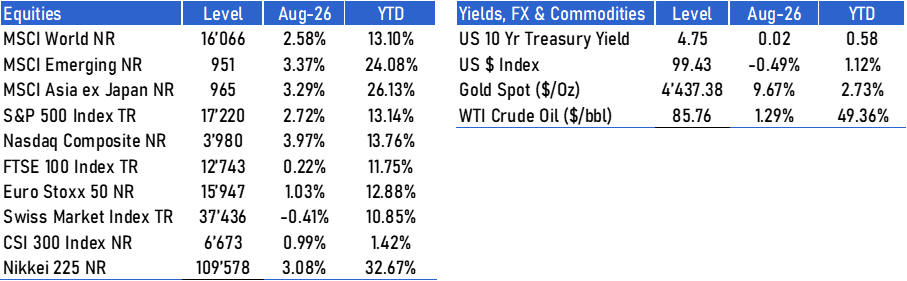
Inflation is still the data point everyone is looking at. The consumer price index is being dissected by its different components and by goods vs services, almost to fit a narrative. It is reassuring that, indeed, the rise in inflation stems mostly from energy prices. The July reading for the US came out at +3.4%. As a reminder, the Federal Reserve’s target and mandate is at +2%. Given the stickiness of inflation, the consensus is for a rise in interest rates in September and potentially another one in December, despite new Fed chair Warsh being perceived as more dovish. He may just not have sufficient votes to keep inflation at current levels.
Despite all the macroeconomic and geopolitical uncertainties, markets focused on the excellent second quarter results, over 80% of companies having beaten profit expectations, resulting in the strongest quarter in recent years.
Europe delivered similar exceptional corporate results in Q2, with over 70% of companies beating profit expectation, leading to the strongest quarter in over 3 years. But just like the US, inflation is also a thorn in the foot of the ECB. The August figure came out at 3.3%, up from 2.9% last month. The central bank is therefore likely to raise interest rates further in September.
In Asia, Japan continues to benefit from the AI hype, despite the joint intervention of the US and Japan to prop up the Yen in late July, which is typically something that Japanese stocks don’t like at all. Here as well, the effect of the intervention is slowly fading as markets have a different view and are always right.
House View
Given the good market performance, we have had multiple products autocalled and took advantage of short-lived volatility events to issue our usual structured products with downside protection.
Being long equities via passive ETF vehicles, we do not need to worry about the rotation happening in the different sectors, thereby avoiding churning the accounts to chase after trends.
Chart of the month
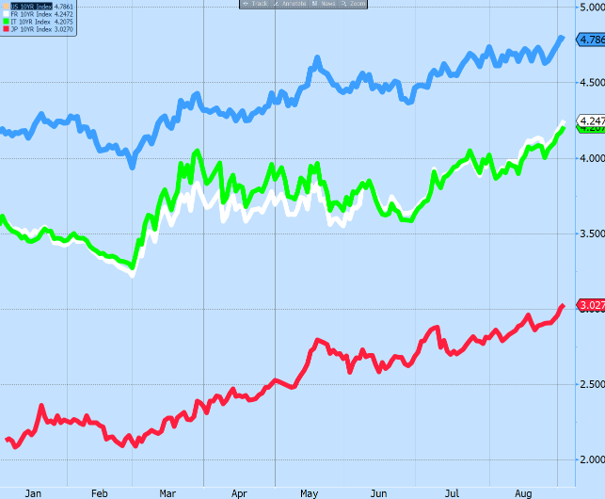
The chart of the month shows the 10-year yield on government bonds from USA (blue), France (white), Italy (green) and Japan (red) since the beginning of the year.
A few things are worth noting. Despite intervention from the US treasury on August 19 to reduce the long end of the yield curve, the impact was very minimal and short lived, almost nonexistent. There are two big reasons for this. For one, investors are starting to reconsider the risk-free nature of US treasuries given the constant budget deficit adding to US debt, now over the 40 trillion mark and a debt to GDP over 120%. Second, competition for capital from hyperscalers is making it more expensive for borrowers.
Another thing worth noting is that the French 10-year yield is higher than the Italian one. This is hard to believe, given that just 15 years ago, Italy was on the verge of collapse from its overwhelming debt, while France and Germany were imposing harsh austerity. Italy has since imposed fiscal discipline and political stability, whereas France is having issues balancing its budget and political will is not there.
Finally, Japan, which had their 10-year bond yield at close to 0% for decades, is now at about 3%. This rise is likely to make it very hard for the country to service its debt with a debt to GDP above 200%. Furthermore, this is having a big impact on global carry-trade, which is the way some investors borrow in currencies with cheap cost of borrowing like Japan to invest elsewhere.
Source: Bloomberg
Disclosures
This document has been issued by Stork Capital, registered with the Swiss Association of Asset Managers, and licensed by FINMA.
Offering Documents. This material is provided at your request for informational purposes only and is not intended as an offer, a solicitation of an offer, to buy, sell or carry out any transaction on investment instruments or other specific product, it only contains selected information with regards to Stork Capital’s services. The analysis and information contained herein do not constitute a personal recommendation or consider the particular investment objectives, investment strategies, financial situation and needs of any specific recipient. Certain services and products are subject to legal restrictions and cannot be offered worldwide on an unrestricted basis and/or may not be eligible for sale to all investors. All information and opinions expressed in this document were obtained from sources believed to be reliable and in good faith, however, Stork Capital cannot guarantee the accuracy of such content, ensure its completeness, or warrant that such information has not or will not change.
Prior to any investment, prospective investors should carefully read the latest offering documentation, including but not limited to the fund’s prospectus which contains inter alia a comprehensive disclosure of applicable risks. The relevant constitutional and offering documents are available free of charge at Stork Capital’s principal office.
Risk Information and Potential Loss. Financial advisers generally suggest a diversified portfolio of investments. The funds described herein do not represent a diversified investment by themselves. This material does not constitute investment advice and should not be used as the basis for any investment decision. This material does not purport to provide any legal, tax or accounting advice. Prospective investors should consult their financial and tax adviser before investing in order to determine whether an investment would be suitable for them.
Any investor or prospective investor should be aware of the risks inherent in trading activity, such as but not limited to currency risk, interest-rate risk, market risk, insolvency risk, and is aware that trading can be very speculative and may result in losses as well as profits. Therefore, an investor should only invest if he/she has the necessary financial resources to bear a complete loss of this investment.
Portfolio Allocations. This material contains information that pertains to past performance or is the basis for previously-made discretionary investment decisions. The value of investments may fall as well as rise and investors may not get back the amount they invested. Thus, past performance does not necessarily provide any guarantee of future results. Accordingly, this information should not be construed as a current recommendation, research or investment advice. It should not be assumed that any investment decisions shown will prove to be profitable, or that any investment decisions made in the future will be profitable or will equal the performance of investments discussed herein. Any mention of an investment decision is intended only to illustrate our investment approach and/or strategy, and is not indicative of the performance of our strategy as a whole. Any such illustration is not necessarily representative of other investment decisions.
Portfolio holdings and/or allocations shown above are as of the date indicated and may not be representative of future investments. The holdings and/or allocations shown may not represent all of the portfolio's investments. Future investments may or may not be profitable.
Intended Recipients. This material and any information contained therein shall only be for the personal use of the intended recipient and shall not be redistributed to any third party, unless Stork Capital or the source of the relevant market data gives their approval. This material is not directed to any person in any jurisdiction where (on the grounds of that person’s nationality, residence or otherwise) such documents are prohibited. In particular, neither this document nor any copy thereof may be sent, taken into or distributed in the United States or to any US person.
Disclaimer of Endorsement. References in these discussion materials to any specific manager, service provider, vendor, market, index, financial procedure, process, resources, or commercial services do not constitute nor imply its endorsement, recommendation, or favour by Stork Capital. Views and opinions expressed are for informational purposes only and do not constitute a recommendation by Stork Capital to buy, sell, or hold any security. Views and opinions are current as of the date of this presentation and may be subject to change, they should not be construed as investment advice. The website links provided are for your convenience only and are not an endorsement or recommendation by Stork Capital of any of these websites or the products or services offered. Stork Capital is not responsible for the accuracy and validity of the content of these websites.
Investment Risks. Risks vary by the type of investment. For example, investments that involve futures, equity swaps, and other derivatives, as well as non-investment grade securities, give rise to substantial risk and are not available to or suitable for all investors. We have described some of the risks associated with certain investments below and, in certain cases, earlier in this presentation. Additional information regarding risks may be available in the materials provided in connection with specific investments. You should not enter into a transaction or make an investment unless you understand the terms of the transaction or investment and the nature and extent of the associated risks. You should also be satisfied that the investment is appropriate for you in light of your circumstances and financial condition.
Alternative Investments. Private investment funds and hedge funds are subject to less regulation than other types of pooled vehicles. Alternative investments may involve a substantial degree of risk, including the risk of total loss of an investor’s capital and the use of leverage, and therefore may not be appropriate for all investors. Liquidity may be limited. Investors should review the Offering Memorandum, the Subscription Agreement and any other applicable disclosures for risks and potential conflicts of interest. Alternative Investments may be subject to less regulation than other types of pooled investment vehicles such as mutual funds. Alternative Investments may impose significant fees, including incentive fees that are based upon a percentage of the realized and unrealized gains and an individual’s net returns may differ significantly from actual returns. Such fees may offset all or a significant portion of such Alternative Investment’s trading profits. Alternative Investments may not be required to provide periodic pricing or valuation information. Investors may have limited rights with respect to their investments, including limited voting rights and participation in the management of such Alternative Investments.
Real Estate. Investments in real estate involve additional risks not typically associated with other asset classes, such as sensitivities to temporary or permanent reductions in property values for the geographic region(s) represented. Real estate investments (both through public and private markets) are also subject to changes in broader macroeconomic conditions, such as interest rates.
The sole place of jurisdiction for all disputes arising out of or in connection with this material and/or the present disclaimer and/or to the use of this material is Geneva, Switzerland, and it shall be exclusively governed by and construed in accordance with Swiss law.