September – Yielding month
The stock market anomaly known as the “September effect” was proven right this year. Markets were down in most major countries and nine out of eleven sectors of the S&P500 receded. In fact, the two sectors that performed well, technology and communication, explain the positive performance of the Nasdaq index.
There is a lot to say about the month, but what stole the headlines is probably the continuing and accelerating trend of yields going up. We will touch on the subject in more detail in the graph of the month section, but in a nutshell, the US Federal Reserve hiking rates this month spilled over the rest of the world, triggering sovereign yields going up pretty much everywhere, even in the forever-zero-interest-rate Switzerland. This is a source of major worry if this goes on, because yields and equity performance are typically negatively correlated, and at some point it just becomes unsustainable for borrowers.
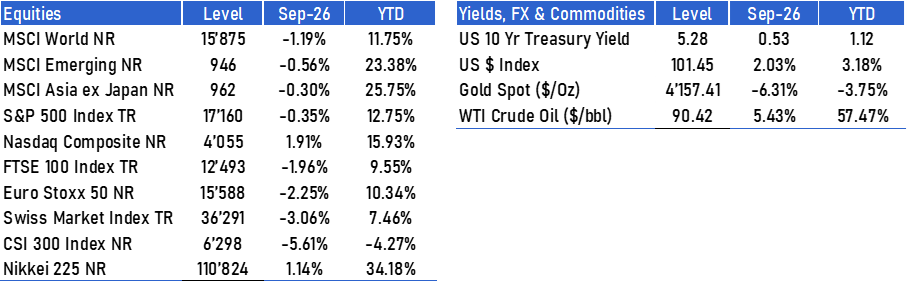
Inflation readings, though the August figure was stable (+3.4%), remain a data point everyone is looking at. As current inflation arises from energy prices, in particular an oil supply shortage, and with demand highly inelastic, bringing it down is not something a single rate hike can solve. Only a peaceful outcome to the conflict in the Middle East will be effective, though looking at the stalled talks around the recent UN assembly, is not for the foreseeable future. We are not alarmed by the current level, as wages growth is at a five-year low, thereby avoiding the vicious circle we could otherwise find ourselves in.
European equities lost ground, ending a 6-month upward streak, mostly as a result of yields going up and inflation fears, after it went up from 3% to 3.2% in August, despite the ECB having raised rates twice over the summer and thereby increasing the prospect of further hikes. But as we wrote further up, this is not the type of inflation a central bank can fight, unless it is willing to completely kill growth. Encouragingly, European PMIs came out at 53.1, the highest level in three and a half years. We can only hope that this translates into higher GDP growth for a region growing in slow motion.
Asia, besides Japan, which was helped by the performance of tech companies and a weaker yen, suffered from the same problems as the rest of the world, namely high energy prices and increasing yields. China completely wiped out the year’s gain and more, despite factory activity rebound, strong tech performance and an economic stimulus.
House View
Given the good market performance this year, we continue to have products autocalled and we take advantage of short-lived volatility events to issue our usual structured products with downside protection. A wise choice, we believe, when markets are at an all-time high despite all the macro and geopolitical headwinds.
Chart of the month
We find the current trend in government debt yields, still considered “risk-free” for many, to be alarming. We have been saying it for months, and the rather violent moves observed support our thesis.
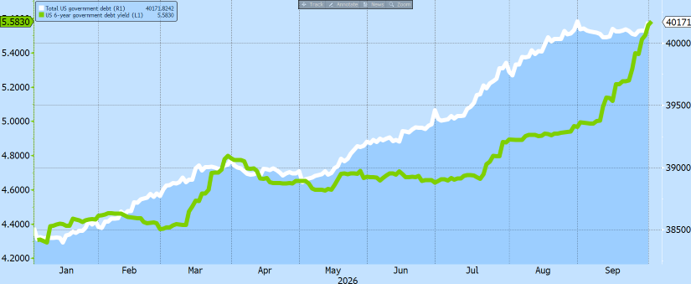
The average US government debt outstanding has a maturity of about 6 years. Therefore, below, in green, we are looking at the 6-year yield curve, which now sits at 5.58%, a level not seen in almost 20 years. Even worse, the 30-year yield curve is flirting with the 7% level.
In white is the total outstanding US debt, which, this month, peaked at the 40 trillion mark.
What this means, using simplified math, is that every year, it will cost the US government over 2.2 trillion just to service the debt.
Other countries are experiencing the same move. The UK 30-year yield touched 6%, a level not seen this millennia. Japan is seeing it’s yields normalizing at brutal speed, going from 3.2% to 5% in less than a year.
As mentioned last month, with lending becoming scarce due to the massive debt build up from hyperscalers, investors are expecting higher returns and rethinking the risk-free nature of many governments, especially in a raising inflation environment.
Source: Bloomberg
Disclosures
This document has been issued by Stork Capital, registered with the Swiss Association of Asset Managers, and licensed by FINMA.
Offering Documents. This material is provided at your request for informational purposes only and is not intended as an offer, a solicitation of an offer, to buy, sell or carry out any transaction on investment instruments or other specific product, it only contains selected information with regards to Stork Capital’s services. The analysis and information contained herein do not constitute a personal recommendation or consider the particular investment objectives, investment strategies, financial situation and needs of any specific recipient. Certain services and products are subject to legal restrictions and cannot be offered worldwide on an unrestricted basis and/or may not be eligible for sale to all investors. All information and opinions expressed in this document were obtained from sources believed to be reliable and in good faith, however, Stork Capital cannot guarantee the accuracy of such content, ensure its completeness, or warrant that such information has not or will not change.
Prior to any investment, prospective investors should carefully read the latest offering documentation, including but not limited to the fund’s prospectus which contains inter alia a comprehensive disclosure of applicable risks. The relevant constitutional and offering documents are available free of charge at Stork Capital’s principal office.
Risk Information and Potential Loss. Financial advisers generally suggest a diversified portfolio of investments. The funds described herein do not represent a diversified investment by themselves. This material does not constitute investment advice and should not be used as the basis for any investment decision. This material does not purport to provide any legal, tax or accounting advice. Prospective investors should consult their financial and tax adviser before investing in order to determine whether an investment would be suitable for them.
Any investor or prospective investor should be aware of the risks inherent in trading activity, such as but not limited to currency risk, interest-rate risk, market risk, insolvency risk, and is aware that trading can be very speculative and may result in losses as well as profits. Therefore, an investor should only invest if he/she has the necessary financial resources to bear a complete loss of this investment.
Portfolio Allocations. This material contains information that pertains to past performance or is the basis for previously-made discretionary investment decisions. The value of investments may fall as well as rise and investors may not get back the amount they invested. Thus, past performance does not necessarily provide any guarantee of future results. Accordingly, this information should not be construed as a current recommendation, research or investment advice. It should not be assumed that any investment decisions shown will prove to be profitable, or that any investment decisions made in the future will be profitable or will equal the performance of investments discussed herein. Any mention of an investment decision is intended only to illustrate our investment approach and/or strategy, and is not indicative of the performance of our strategy as a whole. Any such illustration is not necessarily representative of other investment decisions.
Portfolio holdings and/or allocations shown above are as of the date indicated and may not be representative of future investments. The holdings and/or allocations shown may not represent all of the portfolio's investments. Future investments may or may not be profitable.
Intended Recipients. This material and any information contained therein shall only be for the personal use of the intended recipient and shall not be redistributed to any third party, unless Stork Capital or the source of the relevant market data gives their approval. This material is not directed to any person in any jurisdiction where (on the grounds of that person’s nationality, residence or otherwise) such documents are prohibited. In particular, neither this document nor any copy thereof may be sent, taken into or distributed in the United States or to any US person.
Disclaimer of Endorsement. References in these discussion materials to any specific manager, service provider, vendor, market, index, financial procedure, process, resources, or commercial services do not constitute nor imply its endorsement, recommendation, or favour by Stork Capital. Views and opinions expressed are for informational purposes only and do not constitute a recommendation by Stork Capital to buy, sell, or hold any security. Views and opinions are current as of the date of this presentation and may be subject to change, they should not be construed as investment advice. The website links provided are for your convenience only and are not an endorsement or recommendation by Stork Capital of any of these websites or the products or services offered. Stork Capital is not responsible for the accuracy and validity of the content of these websites.
Investment Risks. Risks vary by the type of investment. For example, investments that involve futures, equity swaps, and other derivatives, as well as non-investment grade securities, give rise to substantial risk and are not available to or suitable for all investors. We have described some of the risks associated with certain investments below and, in certain cases, earlier in this presentation. Additional information regarding risks may be available in the materials provided in connection with specific investments. You should not enter into a transaction or make an investment unless you understand the terms of the transaction or investment and the nature and extent of the associated risks. You should also be satisfied that the investment is appropriate for you in light of your circumstances and financial condition.
Alternative Investments. Private investment funds and hedge funds are subject to less regulation than other types of pooled vehicles. Alternative investments may involve a substantial degree of risk, including the risk of total loss of an investor’s capital and the use of leverage, and therefore may not be appropriate for all investors. Liquidity may be limited. Investors should review the Offering Memorandum, the Subscription Agreement and any other applicable disclosures for risks and potential conflicts of interest. Alternative Investments may be subject to less regulation than other types of pooled investment vehicles such as mutual funds. Alternative Investments may impose significant fees, including incentive fees that are based upon a percentage of the realized and unrealized gains and an individual’s net returns may differ significantly from actual returns. Such fees may offset all or a significant portion of such Alternative Investment’s trading profits. Alternative Investments may not be required to provide periodic pricing or valuation information. Investors may have limited rights with respect to their investments, including limited voting rights and participation in the management of such Alternative Investments.
Real Estate. Investments in real estate involve additional risks not typically associated with other asset classes, such as sensitivities to temporary or permanent reductions in property values for the geographic region(s) represented. Real estate investments (both through public and private markets) are also subject to changes in broader macroeconomic conditions, such as interest rates.
The sole place of jurisdiction for all disputes arising out of or in connection with this material and/or the present disclaimer and/or to the use of this material is Geneva, Switzerland, and it shall be exclusively governed by and construed in accordance with Swiss law.